Semua buku

Profesional

Aplikasi Tentang Pelatih Masuk Mulai membaca

Quantitative Finance · Glosarium

Apa itu Effective breadth, transfer coefficient?

Dikenal juga sebagai: effective breadth · transfer coefficient

Definition 15.5 Research Craft: Predictors, Backtests, Measurement, Portfolios · Bab 15 — From Signal to Forecast

The effective breadth of a set of forecasts is the number of independent forecasts that would give the same information ratio; nn bets with average pairwise correlation ρ\rho are worth about n/(1+(n−1)ρ)n/(1 + (n - 1)\rho). The transfer coefficient of a portfolio is the cross-sectional correlation between its risk-adjusted active weights wiωiw_i\omega_i and the risk-adjusted forecasts αi/ωi\alpha_i/\omega_i.

The information ratio of the planted forecast (IC 0.05, 704 names, monthly): the law’s promise, the book’s with Gaussian residuals, the IC’s mean over its standard deviation and the book’s with the market’s residuals, the generalised law with the long-only transfer coefficient, and the long-only book. Data: rs_forecast.law.
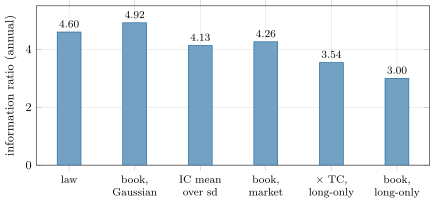
Figure 15.2. The information ratio of the planted forecast (IC 0.05, 704 names, monthly): the law’s promise, the book’s with Gaussian residuals, the IC’s mean over its standard deviation and the book’s with the market’s residuals, the generalised law with the long-only transfer coefficient, and the long-only book. Data: rs_forecast.law.
Baca dalam konteks →