
Tous les livres

Professionnel

Applis À propos Coach Connexion Commencer la lecture

Quantitative Finance · Glossaire

Qu'est-ce que « Equity-implied spread » ?

Definition 9.1 Strategies II: Volatility, Relative Value, Macro and the Bank Desks · Chapitre 9 — Capital-Structure Arbitrage

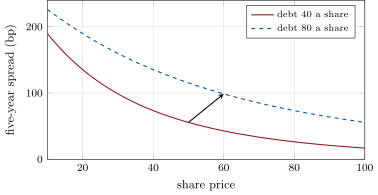
The equity-implied spread of a company is the credit default swap spread that a structural model gives from its share price, equity volatility and debt per share; comparing it with the market spread measures whether the equity and credit markets disagree about the company’s default risk.
The chapter’s equity-implied five-year spread by share price, at 35% equity vol, for debt of 40 and 80 a share. The arrow is a leveraged buyout: the share rises from 50 to 60 on the premium while the debt doubles, and the spread goes from 55.8 to 98.8 basis points. Data: s2_capstruct.curve.
Figure 9.1. The chapter’s equity-implied five-year spread by share price, at 35% equity vol, for debt of 40 and 80 a share. The arrow is a leveraged buyout: the share rises from 50 to 60 on the premium while the debt doubles, and the spread goes from 55.8 to 98.8 basis points. Data: s2_capstruct.curve.
Lire dans le chapitre →