 المدرب
In the escrowed dividend model the share is split into the present value of the dividends to be paid before expiry, treated as riskless, and the rest, , which follows a geometric Brownian motion. European options are priced by Black–Scholes with in place of .
أمثلة
Example 5.5 (One dividend of 4)
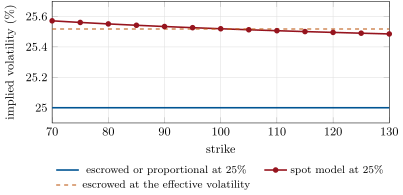
Share 100, one-year options, , a dividend of 4 in six months, spot-model volatility 25%. The escrowed and proportional models at 25% imply a flat 25.00; the spot model’s prices imply 25.57 at the 70 strike and 25.49 at the 130; the effective volatility of the proposition is 25.52 (Figure 5.2). Half a volatility point is 0.2 of premium at the money: a desk that mixes models across systems books it as profit or loss.