Todos los libros

Profesional

Apps Acerca de Coach Iniciar sesión Empezar a leer

Quantitative Finance · Glosario

¿Qué es Escrowed dividend model?

Definition 5.3 Derivatives and Volatility · Capítulo 5 — Dividends, Borrow and Forwards

In the escrowed dividend model the share is split into the present value of the dividends to be paid before expiry, treated as riskless, and the rest, St∗=St−∑t<ti≤TDiP(t,ti)S^*_t=S_t-\sum_{t<t_i\le T}D_iP(t,t_i), which follows a geometric Brownian motion. European options are priced by Black–Scholes with S0∗S^*_0 in place of S0S_0.

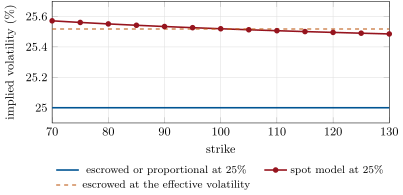
One-year calls on a share at 100 with a dividend of 4 in six months, priced by three dividend models with the same 25% volatility and read back as Black implied volatilities on the common forward. The spot model is half a point above the others and slightly skewed; the effective volatility of  matches it at the money. Data: the tutorial.
Figure 5.2. One-year calls on a share at 100 with a dividend of 4 in six months, priced by three dividend models with the same 25% volatility and read back as Black implied volatilities on the common forward. The spot model is half a point above the others and slightly skewed; the effective volatility of Proposition 5.4 matches it at the money. Data: the tutorial.

Ejemplos

Example 5.5 (One dividend of 4)

Share 100, one-year options, r=3%r=3\%, a dividend of 4 in six months, spot-model volatility 25%. The escrowed and proportional models at 25% imply a flat 25.00; the spot model’s prices imply 25.57 at the 70 strike and 25.49 at the 130; the effective volatility of the proposition is 25.52 (Figure 5.2). Half a volatility point is 0.2 of premium at the money: a desk that mixes models across systems books it as profit or loss.

Leer en el capítulo →