 Pelatih
The forward-rate correlation of a market model is the instantaneous correlation of the Brownian motions driving and . It is usually parametrised, for example , and reduced to two or three factors by keeping the leading eigenvectors of the matrix (the principal components of chapter 3), which speeds simulation and removes noise.
Contoh
Example 8.12 (Same caplets, different swaptions)
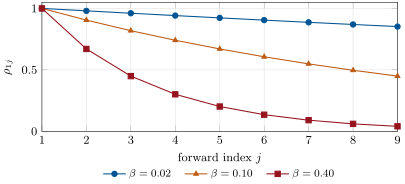
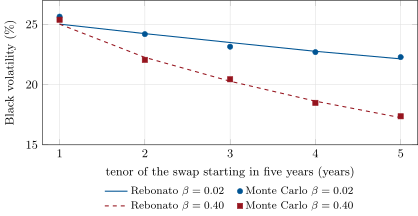
Calibrate the model to the same caplets with (forwards nearly perfectly correlated) and with (the one-year and nine-year forwards correlated at 0.04). The swaption expiring in five years into one year is priced at 25.0% of Black volatility by both (it is one forward); into five years, at 22.1% and 17.3% (Figure 8.5). On EUR 100 million, at the money (forward 2.933%, annuity 4.102), that is EUR 2.35 million against 1.84 million: 22% apart for the same caplets. Monte Carlo confirms Rebonato’s formula to within its standard errors.