All books

Professional

Apps About Coach Log in Start reading

Quantitative Finance · Glossary

What is Forward smile?

Definition 9.8 Derivatives and Volatility · Chapter 9 — Local Volatility

The forward smile from t1t_1 to t2t_2 is the implied volatility, as a function of the relative strike xx, of forward-start options that pay (St2−xSt1)+(S_{t_2}-xS_{t_1})^+ at t2t_2: the smile that the model expects to see at t1t_1 for options of maturity t2−t1t_2-t_1.

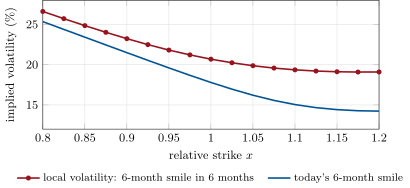
The forward smile of the local volatility model (six-month options starting in six months, by simulation) against today’s six-month smile. The forward smile is higher, because forward variance is higher, and flatter: its at-the-money skew is 57% of today’s. Data: the tutorial.
Figure 9.4. The forward smile of the local volatility model (six-month options starting in six months, by simulation) against today’s six-month smile. The forward smile is higher, because forward variance is higher, and flatter: its at-the-money skew is 57% of today’s. Data: the tutorial.
Read in context →