
جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Fractional Kelly, drawdown, risk of ruin؟

يُعرف أيضًا باسم: fractional Kelly · drawdown · risk of ruin

Definition 29.5 Markets II: Rates, FX and Credit · الفصل 29 — Thinking in Expected Value

Fractional Kelly stakes a multiple c<1c < 1 of the Kelly fraction. A drawdown is a fall of wealth from its previous peak, measured as a fraction of that peak. The risk of ruin of a staking rule is the probability that wealth ever falls to a given fraction of its starting value.
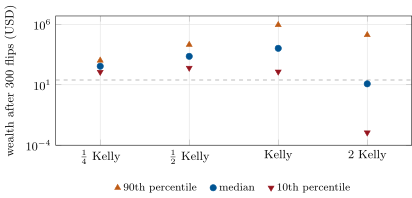
Wealth after 300 flips of the 60% coin from USD 25 (dashed), uncapped, for four multiples of the Kelly fraction, on a log scale: the 10th, 50th and 90th percentiles of 4 000 simulated players each. Kelly has the highest median; half Kelly the best worst tenth; twice Kelly a median below the stake. Data: the chapter’s tutorial, seeded.
Figure 29.2. Wealth after 300 flips of the 60% coin from USD 25 (dashed), uncapped, for four multiples of the Kelly fraction, on a log scale: the 10th, 50th and 90th percentiles of 4 000 simulated players each. Kelly has the highest median; half Kelly the best worst tenth; twice Kelly a median below the stake. Data: the chapter’s tutorial, seeded.
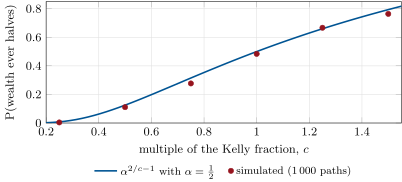
Probability that wealth ever falls to half its starting value, against the multiple of Kelly staked, on a 55% even-money bet: the continuous-time formula and the share of 1 000 simulated paths of 4 000 bets. Data: the chapter’s tutorial, seeded.
Figure 29.3. Probability that wealth ever falls to half its starting value, against the multiple of Kelly staked, on a 55% even-money bet: the continuous-time formula and the share of 1 000 simulated paths of 4 000 bets. Data: the chapter’s tutorial, seeded.
اقرأ في الفصل →