
جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Gilt and liability-driven investment؟

يُعرف أيضًا باسم: gilt · liability-driven investment

Definition 7.6 Markets II: Rates, FX and Credit · الفصل 7 — European and Japanese Government Bonds

A gilt is a UK government bond; conventional gilts pay semiannual coupons, index-linked gilts pay coupons and principal indexed to inflation. Liability-driven investment (LDI) is a strategy in which a defined-benefit pension fund hedges the interest-rate and inflation sensitivity of its liabilities with long gilts and swaps, often with leverage from repo and derivatives, so that it can hedge more of its liabilities than it holds in bonds while keeping other, higher-returning assets.
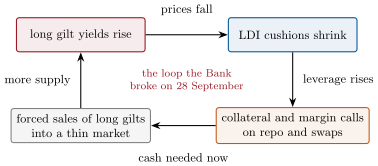
The collateral spiral of September 2022. Pension-fund LDI strategies borrowed against long gilts; rising yields eroded their cushions, calls for collateral could be met fastest by selling gilts, and the selling raised yields further. A buyer that could absorb the sales without needing a return, the central bank, stopped the loop.
Figure 7.3. The collateral spiral of September 2022. Pension-fund LDI strategies borrowed against long gilts; rising yields eroded their cushions, calls for collateral could be met fastest by selling gilts, and the selling raised yields further. A buyer that could absorb the sales without needing a return, the central bank, stopped the loop.
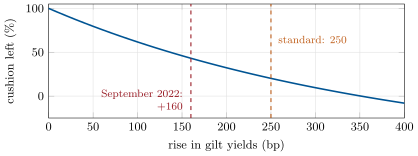
The cushion of an illustrative LDI fund, two-times levered in repo and holding a thirty-year gilt, as gilt yields rise from 3.5%. It falls to 43% of its starting value after 160 basis points, the size of the September 2022 move, and to zero after 351. Data: the chapter’s weekend problem.
Figure 7.4. The cushion of an illustrative LDI fund, two-times levered in repo and holding a thirty-year gilt, as gilt yields rise from 3.5%. It falls to 43% of its starting value after 160 basis points, the size of the September 2022 move, and to zero after 351. Data: the chapter’s weekend problem.
اقرأ في الفصل →