Coach
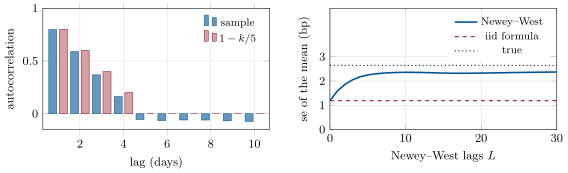
A heteroskedasticity- and autocorrelation-consistent (HAC estimator) estimates a long-run variance by weighting sample autocovariances; the Newey–West estimator uses Bartlett weights, which keep it nonnegative, with a bandwidth growing slowly with (a common rule is ).