Todos los libros

Profesional

Apps Acerca de Coach Iniciar sesión Empezar a leer

Quantitative Finance · Glosario

¿Qué es Hawkes process, excitation kernel, branching ratio?

También llamado: Hawkes process · excitation kernel · branching ratio

Definition 7.4 Quantitative Methods · Capítulo 7 — Point Processes and Hawkes Processes

A Hawkes process is a counting process with intensity

λt=μ+∑ti<tg(t−ti),\lambda_t = \mu + \sum_{t_i < t}g(t - t_i),

with a baseline μ>0\mu > 0 and a nonnegative excitation kernel gg. The branching ratio is ∥g∥1=∫0∞g(u) du\lVert g\rVert_1 = \int_0^\infty g(u)\,du. With the exponential kernel g(u)=αe−βug(u) = \alpha e^{-\beta u}, it is α/β\alpha/\beta.

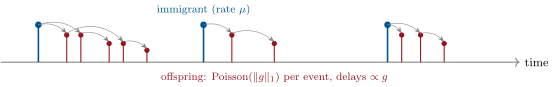
The cluster representation of a Hawkes process. Immigrants (tall, blue) arrive as a Poisson process; every event has a Poisson number of children (short, red) with mean equal to the branching ratio, at delays drawn from the normalised kernel. The events of all generations together form the Hawkes process.
Figure 7.1. The cluster representation of a Hawkes process. Immigrants (tall, blue) arrive as a Poisson process; every event has a Poisson number of children (short, red) with mean equal to the branching ratio, at delays drawn from the normalised kernel. The events of all generations together form the Hawkes process.
Leer en el capítulo →