
Todos os livros

Profissional

Apps Sobre Coach Entrar Começar a ler

Quantitative Finance · Glossário

O que é IC information ratio, quantile spread?

Também chamado de: IC information ratio · quantile spread

Definition 6.7 Research Craft: Predictors, Backtests, Measurement, Portfolios · Capítulo 6 — Anatomy of a Predictor

The IC information ratio (ICIR) is the mean IC divided by its standard deviation over dates, annualised by 252/h\sqrt{252/h} for an hh-day horizon sampled every hh days. The quantile spread is the mean target of the securities in the predictor’s top quantile minus that of the bottom quantile, date by date.
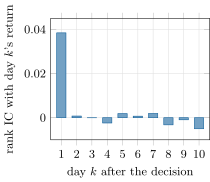
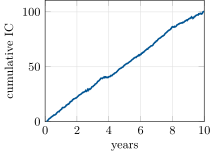
The one-day reversal on the synthetic market. Left: its rank IC with the return of each of the next ten days; the information is spent on the first day (0.0385), the second has 0.0008. Right: the cumulative sum of its daily IC over ten years, neutralised to beta and industries; a straight line is a stable predictor. Data: firm.synthmkt, seed 1. The one-day reversal on the synthetic market. Left: its rank IC with the return of each of the next ten days; the information is spent on the first day (0.0385), the second has 0.0008. Right: the cumulative sum of its daily IC over ten years, neutralised to beta and industries; a straight line is a stable predictor. Data: firm.synthmkt, seed 1.
Figure 6.3. The one-day reversal on the synthetic market. Left: its rank IC with the return of each of the next ten days; the information is spent on the first day (0.0385), the second has 0.0008. Right: the cumulative sum of its daily IC over ten years, neutralised to beta and industries; a straight line is a stable predictor. Data: firm.synthmkt, seed 1.
Ler no capítulo →