
جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Implied policy path؟

Definition 8.5 Markets II: Rates, FX and Credit · الفصل 8 — Short-Term Interest-Rate Futures

The implied policy path is the sequence of policy rates the market expects after each scheduled meeting of the central bank, read from the prices of short-term interest-rate futures (or overnight index swaps) as if those prices were expectations, any risk premium neglected.
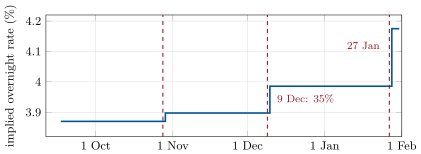
The path of the overnight rate implied by the illustrative one-month contracts of , stepping at each decision (dashed). The steps are expectations, averages over hold and hike, not forecasts of a quarter-point move: 35% of 25 basis points is the 8.8 of December. Data: the chapter’s tutorial.
Figure 8.2. The path of the overnight rate implied by the illustrative one-month contracts of Example 8.7, stepping at each decision (dashed). The steps are expectations, averages over hold and hike, not forecasts of a quarter-point move: 35% of 25 basis points is the 8.8 of December. Data: the chapter’s tutorial.
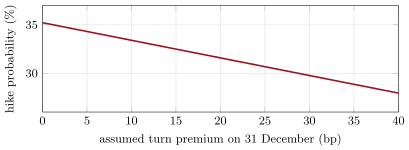
The December hike probability implied by the same price as the year-end turn assumed on the 31 December fixing grows: 35.2% with no turn, 33.4% with 10 basis points, 0.18 percentage points less for each basis point of turn. The turn is a money-market fact () that a policy reading must remove first. Data: the chapter’s weekend problem.
Figure 8.3. The December hike probability implied by the same price as the year-end turn assumed on the 31 December fixing grows: 35.2% with no turn, 33.4% with 10 basis points, 0.18 percentage points less for each basis point of turn. The turn is a money-market fact (Chapter 2) that a policy reading must remove first. Data: the chapter’s weekend problem.

أمثلة

Example 8.7 (Three meetings)

From a rate of 3.87% after the September 2026 decision, with illustrative prices of 96.1275 (October), 96.1025 (November), 96.040 (December) and 95.990 (January 2027): the November contract implies 3.8975% after the October meeting, an 11% chance of a hike; December implies 3.9856% after the 9 December meeting, a 35% chance; January implies 4.175% after the 27 January meeting (Figure 8.2).

اقرأ في الفصل →