 Pelatih
The implied policy path is the sequence of policy rates the market expects after each scheduled meeting of the central bank, read from the prices of short-term interest-rate futures (or overnight index swaps) as if those prices were expectations, any risk premium neglected.
Contoh
Example 8.7 (Three meetings)
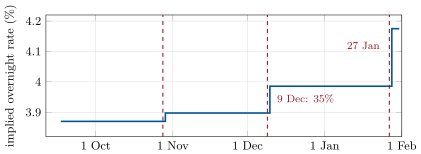
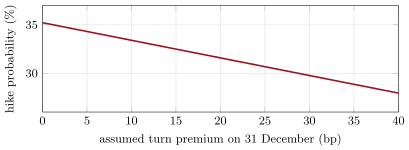
From a rate of 3.87% after the September 2026 decision, with illustrative prices of 96.1275 (October), 96.1025 (November), 96.040 (December) and 95.990 (January 2027): the November contract implies 3.8975% after the October meeting, an 11% chance of a hike; December implies 3.9856% after the 9 December meeting, a 35% chance; January implies 4.175% after the 27 January meeting (Figure 8.2).