
Todos os livros

Profissional

Apps Sobre Coach Entrar Começar a ler

Quantitative Finance · Glossário

O que é Implied-price arbitrage?

Definition 15.2 Market Making and High-Frequency Trading · Capítulo 15 — Futures Market Making

Implied-price arbitrage is trading a spread book against its two outright books when the spread’s direct price is outside the range implied by the outrights (or the reverse), before the exchange’s implied matching or other traders close the gap.
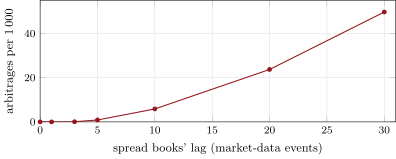
Implied-price arbitrages between three calendar-spread books and four outright books, per thousand spread-book observations, against how many market-data events the spread books’ quotes lag the outrights; the curve’s level and slope move 0.6 and 0.4 ticks an event; 5 000 events. Data: hf_futures.implied.
Figure 15.2. Implied-price arbitrages between three calendar-spread books and four outright books, per thousand spread-book observations, against how many market-data events the spread books’ quotes lag the outrights; the curve’s level and slope move 0.6 and 0.4 ticks an event; 5 000 events. Data: hf_futures.implied.
Ler no capítulo →