
جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Interpolation locality؟

Definition 1.11 Rates, Credit, XVA and Risk · الفصل 1 — Curve Construction

An interpolation scheme has interpolation locality if a change in one input quote changes the curve only near that input’s maturity. Locality decides what a bucketed hedge looks like: under a local scheme an off-pillar swap is hedged with the pillars around it; under a non-local one it acquires risk, of either sign, on pillars far from its maturity.
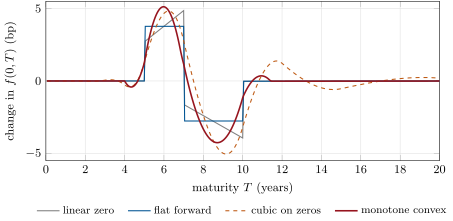
The response of the forward curve to a one-basis-point rise in the seven-year swap quote, with the curve recalibrated. Flat forwards move only between five and ten years (up before seven, down after, so that the ten-year swap still reprices); the monotone convex curve adds small ripples just outside that span; the cubic spline moves the forwards from three years to beyond twenty. Data: the chapter’s tutorial.
Figure 1.4. The response of the forward curve to a one-basis-point rise in the seven-year swap quote, with the curve recalibrated. Flat forwards move only between five and ten years (up before seven, down after, so that the ten-year swap still reprices); the monotone convex curve adds small ripples just outside that span; the cubic spline moves the forwards from three years to beyond twenty. Data: the chapter’s tutorial.
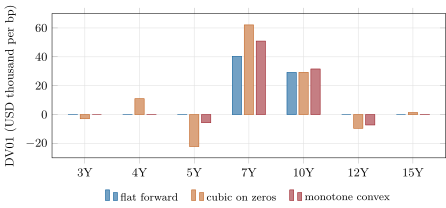
Bucketed DV01 of an eight-year par payer swap of USD 100 million by input quote, for three interpolations (each quote bumped by a hundredth of a basis point, curve recalibrated, result scaled to one basis point). The eight-year date lies between the seven- and ten-year pillars; flat forwards load only those two, monotone convex adds small five- and twelve-year buckets, the cubic spline large ones of both signs from three to fifteen years. Data: the chapter’s tutorial.
Figure 1.5. Bucketed DV01 of an eight-year par payer swap of USD 100 million by input quote, for three interpolations (each quote bumped by a hundredth of a basis point, curve recalibrated, result scaled to one basis point). The eight-year date lies between the seven- and ten-year pillars; flat forwards load only those two, monotone convex adds small five- and twelve-year buckets, the cubic spline large ones of both signs from three to fifteen years. Data: the chapter’s tutorial.

أمثلة

Example 1.12 (An eight-year swap on four curves)

A par payer swap of USD 100 million for eight years has a parallel DV01 of about USD 69 600 on all four curves: they agree on the level. They disagree on where it sits (Figure 1.5). Flat forwards put USD 40 400 on the seven-year quote and USD 29 200 on the ten-year; the cubic spline puts USD 62 100 on seven years, −22 200-22\,200 on five, +11 000+11\,000 on four and −9 500-9\,500 on twelve; monotone convex lies in between. Each set of buckets sums to the parallel DV01, and each asks for a different hedge.

اقرأ في الفصل →