
Alle boeken

Professioneel

Apps Over Coach Inloggen Begin met lezen

Quantitative Finance · Begrippenlijst

Wat is Interpolation locality?

Definition 1.11 Rates, Credit, XVA and Risk · Hoofdstuk 1 — Curve Construction

An interpolation scheme has interpolation locality if a change in one input quote changes the curve only near that input’s maturity. Locality decides what a bucketed hedge looks like: under a local scheme an off-pillar swap is hedged with the pillars around it; under a non-local one it acquires risk, of either sign, on pillars far from its maturity.
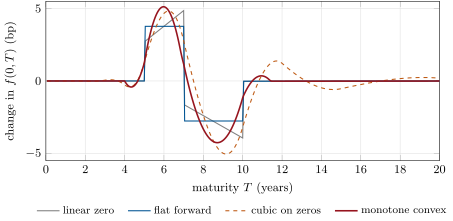
The response of the forward curve to a one-basis-point rise in the seven-year swap quote, with the curve recalibrated. Flat forwards move only between five and ten years (up before seven, down after, so that the ten-year swap still reprices); the monotone convex curve adds small ripples just outside that span; the cubic spline moves the forwards from three years to beyond twenty. Data: the chapter’s tutorial.
Figure 1.4. The response of the forward curve to a one-basis-point rise in the seven-year swap quote, with the curve recalibrated. Flat forwards move only between five and ten years (up before seven, down after, so that the ten-year swap still reprices); the monotone convex curve adds small ripples just outside that span; the cubic spline moves the forwards from three years to beyond twenty. Data: the chapter’s tutorial.
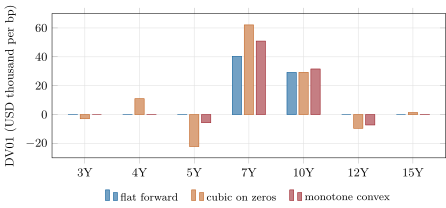
Bucketed DV01 of an eight-year par payer swap of USD 100 million by input quote, for three interpolations (each quote bumped by a hundredth of a basis point, curve recalibrated, result scaled to one basis point). The eight-year date lies between the seven- and ten-year pillars; flat forwards load only those two, monotone convex adds small five- and twelve-year buckets, the cubic spline large ones of both signs from three to fifteen years. Data: the chapter’s tutorial.
Figure 1.5. Bucketed DV01 of an eight-year par payer swap of USD 100 million by input quote, for three interpolations (each quote bumped by a hundredth of a basis point, curve recalibrated, result scaled to one basis point). The eight-year date lies between the seven- and ten-year pillars; flat forwards load only those two, monotone convex adds small five- and twelve-year buckets, the cubic spline large ones of both signs from three to fifteen years. Data: the chapter’s tutorial.

Voorbeelden

Example 1.12 (An eight-year swap on four curves)

A par payer swap of USD 100 million for eight years has a parallel DV01 of about USD 69 600 on all four curves: they agree on the level. They disagree on where it sits (Figure 1.5). Flat forwards put USD 40 400 on the seven-year quote and USD 29 200 on the ten-year; the cubic spline puts USD 62 100 on seven years, −22 200-22\,200 on five, +11 000+11\,000 on four and −9 500-9\,500 on twelve; monotone convex lies in between. Each set of buckets sums to the parallel DV01, and each asks for a different hedge.

Lees in het hoofdstuk →