All books

Professional

Apps About Coach Log in Start reading

Quantitative Finance · Glossary

What is Inventory penalty?

Definition 3.5 Market Making and High-Frequency Trading · Chapter 3 — Inventory Models

An inventory penalty replaces risk aversion in utility by a cost charged on the position while it is held: the market maker maximises E[XT+qTST−αqT2−ϕ∫0Tqt2 dt]\E\bigl[X_T+q_TS_T-\alpha q_T^2-\phi\int_0^Tq_t^2\,dt\bigr], with a running penalty ϕ\phi and a terminal one α\alpha.

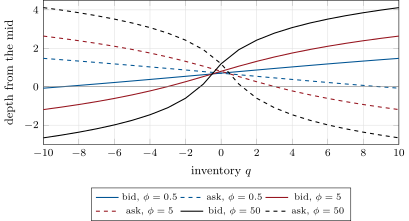
Optimal bid depth (solid) and ask depth (dashed) at the start of the session against inventory, for three running penalties  (; A=140, k=1.5, T=1, =1, inventory within ±30). Below zero the ask is offered under the mid. Data: firm.invmm.CJSolution.
Figure 3.1. Optimal bid depth (solid) and ask depth (dashed) at the start of the session against inventory, for three running penalties ϕ\phi (Proposition 3.6; A=140A=140, k=1.5k=1.5, T=1T=1, α=1\alpha=1, inventory within ±30\pm30). Below zero the ask is offered under the mid. Data: firm.invmm.CJSolution.
Read in context →