Semua buku

Profesional

Aplikasi Tentang Pelatih Masuk Mulai membaca

Quantitative Finance · Glosarium

Apa itu Kalman filter, innovation, Kalman gain?

Dikenal juga sebagai: Kalman filter · innovation · Kalman gain

Definition 19.3 Quantitative Methods · Bab 19 — State-Space Models and the Kalman Filter

The Kalman filter (Kalman, 1960) computes recursively the conditional law αt∣y1,…,yt−1∼N(at,Pt)\alpha_t \mid y_1, \dots, y_{t-1} \sim \mathcal N(a_t, P_t). Given (at,Pt)(a_t, P_t), the innovation is vt=yt−Ztatv_t = y_t - Z_ta_t, with variance Ft=ZtPtZt⊤+HF_t = Z_tP_tZ_t^\top + H; the Kalman gain Kt=PtZt⊤Ft−1K_t = P_tZ_t^\top F_t^{-1} updates the state, at∣t=at+Ktvta_{t|t} = a_t + K_tv_t and Pt∣t=Pt−KtZtPtP_{t|t} = P_t - K_tZ_tP_t, and the prediction step gives at+1=Tat∣ta_{t+1} = Ta_{t|t} and Pt+1=TPt∣tT⊤+QP_{t+1} = TP_{t|t}T^\top + Q.

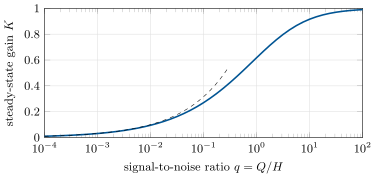
Steady-state Kalman gain of the local level model against the signal-to-noise ratio, K = p/(1 + p) with p = (q + √q2 + 4q)/2, and its small-q approximation √ q (dashed). At q = 0.01 the filter puts 9.5% weight on each new observation; at q = 1, 62%. Data: the chapter’s formula.
Figure 19.1. Steady-state Kalman gain of the local level model against the signal-to-noise ratio, K=p/(1+p)K = p/(1 + p) with p=(q+q2+4q)/2p = (q + \sqrt{q^2 + 4q})/2, and its small-qq approximation q\sqrt q (dashed). At q=0.01q = 0.01 the filter puts 9.5% weight on each new observation; at q=1q = 1, 62%. Data: the chapter’s formula.
Baca dalam konteks →