
جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Legging risk؟

Definition 13.2 Market Making and High-Frequency Trading · الفصل 13 — Index and Basket Arbitrage

Legging risk is the risk that the prices of the legs of a multi-instrument trade move between the execution of the first leg and the last, so that the trade completes at worse prices than those that justified it, or does not complete.
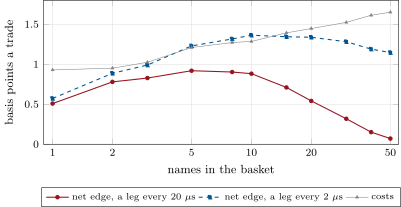
Net edge per trade (capture less costs, basis points of the notional) against the size of the partial basket, when the future jumps 3 basis points and each stock’s quote follows after an exponential delay of mean 400 microseconds; legs sent every 20 or every 2 microseconds; costs are the legs’ and the future’s half-spreads in and out. 20 000 trades per point. Data: hf_basket.sweep.
Figure 13.1. Net edge per trade (capture less costs, basis points of the notional) against the size of the partial basket, when the future jumps 3 basis points and each stock’s quote follows after an exponential delay of mean 400 microseconds; legs sent every 20 or every 2 microseconds; costs are the legs’ and the future’s half-spreads in and out. 20 000 trades per point. Data: hf_basket.sweep.
اقرأ في الفصل →