
Alle boeken

Professioneel

Apps Over Coach Inloggen Begin met lezen

Quantitative Finance · Begrippenlijst

Wat is Legging risk?

Definition 13.2 Market Making and High-Frequency Trading · Hoofdstuk 13 — Index and Basket Arbitrage

Legging risk is the risk that the prices of the legs of a multi-instrument trade move between the execution of the first leg and the last, so that the trade completes at worse prices than those that justified it, or does not complete.
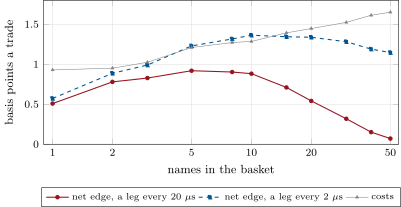
Net edge per trade (capture less costs, basis points of the notional) against the size of the partial basket, when the future jumps 3 basis points and each stock’s quote follows after an exponential delay of mean 400 microseconds; legs sent every 20 or every 2 microseconds; costs are the legs’ and the future’s half-spreads in and out. 20 000 trades per point. Data: hf_basket.sweep.
Figure 13.1. Net edge per trade (capture less costs, basis points of the notional) against the size of the partial basket, when the future jumps 3 basis points and each stock’s quote follows after an exponential delay of mean 400 microseconds; legs sent every 20 or every 2 microseconds; costs are the legs’ and the future’s half-spreads in and out. 20 000 trades per point. Data: hf_basket.sweep.
Lees in het hoofdstuk →