Semua buku

Profesional

Aplikasi Tentang Pelatih Masuk Mulai membaca

Quantitative Finance · Glosarium

Apa itu Leisen–Reimer tree?

Dikenal juga sebagai: Leisen--Reimer tree

Definition 2.8 Derivatives and Volatility · Bab 2 — The Binomial Model

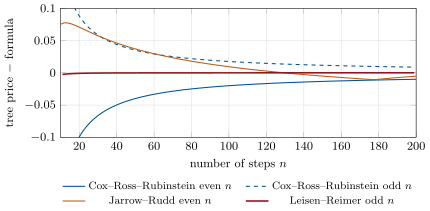
The Leisen–Reimer tree uses an odd number of steps and chooses pp and uu so that the tree’s probabilities of finishing above the strike, under the risk-neutral and the share measures, equal Φ(d2)\Phi(d_2) and Φ(d1)\Phi(d_1) (through a normal-to-binomial inversion due to Peizer and Pratt). The tree is centred on the strike, and the error for European options falls like 1/n21/n^2 without oscillation.

Error of three trees for the one-year at-the-money European put (r=5\%, =20\%, formula 5.5735), even and odd step counts drawn separately. The Cox–Ross–Rubinstein error is negative for even n, positive for odd n, and shrinks like 1/n; the Leisen–Reimer error is invisible at this scale from 11 steps. Data: the tutorial.
Figure 2.3. Error of three trees for the one-year at-the-money European put (r=5%r=5\%, σ=20%\sigma=20\%, formula 5.5735), even and odd step counts drawn separately. The Cox–Ross–Rubinstein error is negative for even nn, positive for odd nn, and shrinks like 1/n1/n; the Leisen–Reimer error is invisible at this scale from 11 steps. Data: the tutorial.
Baca dalam konteks →