
Tous les livres

Professionnel

Applis À propos Coach Connexion Commencer la lecture

Quantitative Finance · Glossaire

Qu'est-ce que « Linear, inverse and quanto contracts » ?

Aussi appelé : linear contract · inverse contract · quanto contract

Definition 17.6 Markets III: Commodities, Energy and Crypto · Chapitre 17 — Perpetual Futures

A linear contract is quoted and settled in the quote currency (a dollar or a stablecoin), its P&L linear in the price: q (S−E)q\,(S - E) for qq units bought at EE. An inverse contract has a fixed notional in the quote currency but is margined and settled in the underlying coin, so that NN contracts of one dollar each bought at EE earn N (1/E−1/S)N\,(1/E - 1/S) coins. A quanto contract is quoted on one asset but margined and settled in another at a fixed rate per unit of price move, so that its P&L in the settlement asset is N m (S−E)N\,m\,(S - E) for a multiplier mm, whatever the settlement asset’s price.
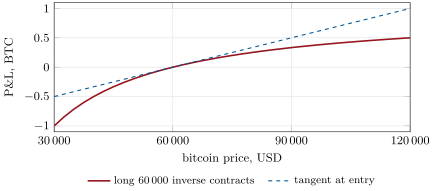
P&L in bitcoin of a long position of 60 000 one-dollar inverse contracts entered at USD 60 000 (): a fall to 30 000 costs a whole bitcoin, a rise to 120 000 gains only half of one. The curve lies below its tangent: a long inverse position is short convexity in coin. Data: the chapter’s tutorial.
Figure 17.3. P&L in bitcoin of a long position of 60 000 one-dollar inverse contracts entered at USD 60 000 (Proposition 17.7): a fall to 30 000 costs a whole bitcoin, a rise to 120 000 gains only half of one. The curve lies below its tangent: a long inverse position is short convexity in coin. Data: the chapter’s tutorial.
Lire dans le chapitre →