
جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Lognormal volatility؟

Definition 4.2 Rates, Credit, XVA and Risk · الفصل 4 — Vanilla Rates Options

The lognormal volatility σB\sigma_B of a rates option is the volatility at which Black’s formula, applied to the forward rate, reproduces its price; it is a relative volatility, a percentage of the rate, and exists only for positive forward and strike.
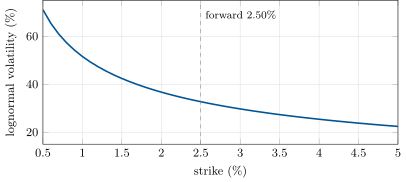
The lognormal (Black) implied volatility of five-year options on a forward of 2.50% priced with a single normal volatility of 80 basis points. A flat normal smile is a steep lognormal skew. Data: the chapter’s tutorial.
Figure 4.1. The lognormal (Black) implied volatility of five-year options on a forward of 2.50% priced with a single normal volatility of 80 basis points. A flat normal smile is a steep lognormal skew. Data: the chapter’s tutorial.

أمثلة

Example 4.8 (Five years into ten)

On chapter 2’s curves the ten-year swap starting in five years has a forward par rate of 3.098% against six-month Euribor and a (discount-curve) annuity of 7.740. At 80 basis points of normal volatility (a lognormal volatility of 26.2%), the at-the-money physical payer on EUR 100 million is worth EUR 5 525 150. The traditional cash formula, P(0,T) a(S0)×P(0,T)\,a(S_0)\times option, gives EUR 5 410 452, 2.1% less: P(0,T) a(S0)=7.579P(0,T)\,a(S_0) = 7.579, because the cash annuity discounts at the Euribor swap rate, above the €STR rates of the collateralised annuity. The par-yield payoff is also not a function of the annuity measure’s numeraire, so the formula is itself an approximation; the collateralised cash price removes both problems by settling at the physical value.

اقرأ في الفصل →