Todos os livros

Profissional

Apps Sobre Coach Entrar Começar a ler

Quantitative Finance · Glossário

O que é Lookback option?

Definition 16.3 Derivatives and Volatility · Capítulo 16 — Asians, Lookbacks, Cliquets and Forward-Starts

A lookback option pays on the maximum or minimum of the underlying over its life. The floating-strike lookback call pays ST−min⁡tStS_T-\min_tS_t (buy at the low); the fixed-strike lookback call pays (max⁡tSt−K)+(\max_tS_t-K)^+.

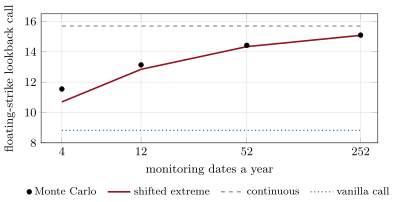
The floating-strike lookback call (one year, 20%, r=3\%, q=1\%) by monitoring frequency: simulation, the continuous formula of Goldman, Sosin and Gatto, and the same with the extreme shifted as a barrier is. Data: the tutorial.
Figure 16.2. The floating-strike lookback call (one year, 20%, r=3%r=3\%, q=1%q=1\%) by monitoring frequency: simulation, the continuous formula of Goldman, Sosin and Gatto, and the same with the extreme shifted as a barrier is. Data: the tutorial.
Ler no capítulo →