
Alle boeken

Professioneel

Apps Over Coach Inloggen Begin met lezen

Quantitative Finance · Begrippenlijst

Wat is Loss-versus-rebalancing?

Definition 20.8 Markets III: Commodities, Energy and Crypto · Hoofdstuk 20 — Automated Market Makers

Loss-versus-rebalancing (LVR) is the difference between the value of a rebalancing portfolio that tracks an automated market maker’s holdings by trading at market prices and the value of the pool itself; it is the amount the pool loses to arbitrageurs by trading at its own stale prices rather than at the market’s.
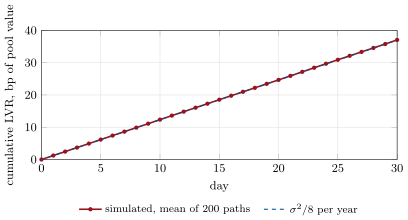
Loss-versus-rebalancing of a fee-free constant-product pool: the rebalancing portfolio minus the pool, averaged over 200 simulated paths at 60% annual volatility with arbitrage every 15 minutes, against the closed form of ; the two lines coincide. Data: the chapter’s tutorial.
Figure 20.3. Loss-versus-rebalancing of a fee-free constant-product pool: the rebalancing portfolio minus the pool, averaged over 200 simulated paths at 60% annual volatility with arbitrage every 15 minutes, against the closed form of Proposition 20.9; the two lines coincide. Data: the chapter’s tutorial.
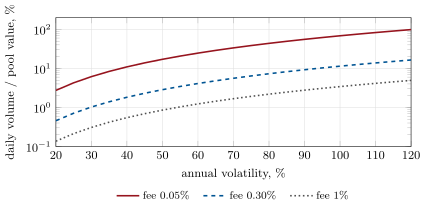
The daily turnover by noise traders at which a constant-product pool’s fees equal its loss-versus-rebalancing (), for three fee tiers. Data: the chapter’s tutorial.
Figure 20.4. The daily turnover by noise traders at which a constant-product pool’s fees equal its loss-versus-rebalancing (Proposition 20.10), for three fee tiers. Data: the chapter’s tutorial.
Lees in het hoofdstuk →