Tous les livres

Professionnel

Applis À propos Coach Connexion Commencer la lecture

Quantitative Finance · Glossaire

Qu'est-ce que « Method of simulated moments » ?

Definition 27.4 Microstructure and Execution · Chapitre 27 — Build: an Agent-Based Market

The method of simulated moments estimates the parameters of a model that can be simulated but whose moments have no closed form: it chooses the parameters that minimise a weighted distance between moments computed from the data and the same moments averaged over simulations of the model, the simulations using the same random draws at every candidate parameter.
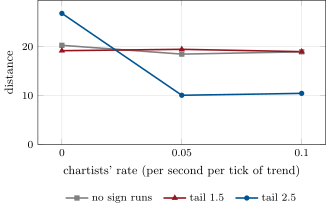
The distance between simulated and target facts at a noise rate of 1.2 orders a second, by the chartists’ rate and the run tail, three hours per point with the same seeds. Data: mx_agents.calibration.
Figure 27.4. The distance between simulated and target facts at a noise rate of 1.2 orders a second, by the chartists’ rate and the run tail, three hours per point with the same seeds. Data: mx_agents.calibration.
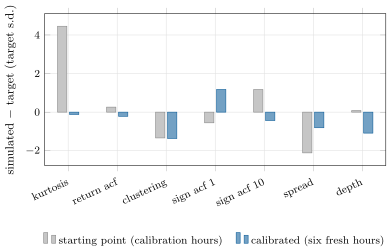
Each fact’s gap to the target in target standard deviations, for the starting point and for the calibrated population. The squares of the calibrated bars sum to the distance on fresh hours. Data: mx_agents.calibration.
Figure 27.5. Each fact’s gap to the target in target standard deviations, for the starting point and for the calibrated population. The squares of the calibrated bars sum to the distance on fresh hours. Data: mx_agents.calibration.
Lire dans le chapitre →