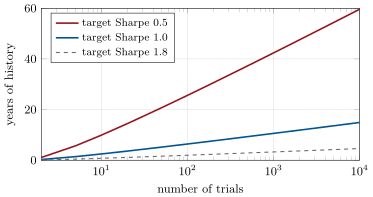
The minimum backtest length for trials and a target Sharpe ratio is the number of years of history below which the expected best of strategies with no skill has an in-sample Sharpe ratio at or above the target.
firm.overfit.min_backtest_length. Coach
Log in
Start reading
Quantitative Finance · Glossary
The minimum backtest length for trials and a target Sharpe ratio is the number of years of history below which the expected best of strategies with no skill has an in-sample Sharpe ratio at or above the target.
firm.overfit.min_backtest_length.