
جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Monotone convex interpolation؟

Definition 1.7 Rates, Credit, XVA and Risk · الفصل 1 — Curve Construction

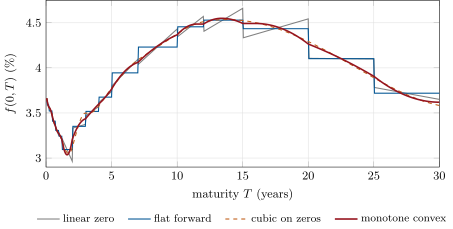
Monotone convex interpolation (Hagan and West, 2006) builds the forward curve directly. On each interval it keeps the discrete forward fˉj\bar f_j, estimates the instantaneous forward fjf_j at each pillar as the time-weighted average of the two adjacent discrete forwards, and fills the interval with f(T)=fˉj+G(x)f(T)=\bar f_j + G(x), x=(T−Tj−1)/(Tj−Tj−1)x=(T-T_{j-1})/(T_j-T_{j-1}), where GG is a quadratic, or a quadratic joined to a constant, with G(0)=fj−1−fˉjG(0)=f_{j-1}-\bar f_j, G(1)=fj−fˉjG(1)=f_j-\bar f_j and ∫01G=0\int_0^1G=0, chosen from four cases so that GG never overshoots its end values. The forward curve is continuous, reproduces every discrete forward, and stays within the range of the neighbouring forwards.
Four instantaneous forward curves from the same seventeen quotes; every one reprices every input exactly. Linear zero rates give a sawtooth; flat forwards give steps; the cubic spline and the monotone convex curve are continuous and nearly coincide at this scale: they differ in how they respond to a change of one quote (). Data: the chapter’s illustrative dollar curve and tutorial.
Figure 1.2. Four instantaneous forward curves from the same seventeen quotes; every one reprices every input exactly. Linear zero rates give a sawtooth; flat forwards give steps; the cubic spline and the monotone convex curve are continuous and nearly coincide at this scale: they differ in how they respond to a change of one quote (Figure 1.4). Data: the chapter’s illustrative dollar curve and tutorial.
اقرأ في الفصل →