Pelatih
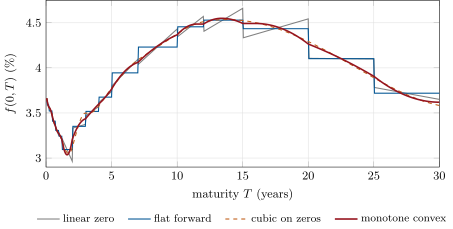
Monotone convex interpolation (Hagan and West, 2006) builds the forward curve directly. On each interval it keeps the discrete forward , estimates the instantaneous forward at each pillar as the time-weighted average of the two adjacent discrete forwards, and fills the interval with , , where is a quadratic, or a quadratic joined to a constant, with , and , chosen from four cases so that never overshoots its end values. The forward curve is continuous, reproduces every discrete forward, and stays within the range of the neighbouring forwards.