Semua buku

Profesional

Aplikasi Tentang Pelatih Masuk Mulai membaca

Quantitative Finance · Glosarium

Apa itu Multilevel Monte Carlo?

Definition 26.13 Quantitative Methods · Bab 26 — Monte Carlo

Multilevel Monte Carlo (Giles, 2008) writes the finest-level expectation as a telescoping sum EPL=EP0+∑l=1LE[Pl−Pl−1]\E P_L = \E P_0 + \sum_{l=1}^L\E[P_l - P_{l-1}], where PlP_l is the payoff computed with step hl=2−lTh_l = 2^{-l}T, and estimates each term independently, with PlP_l and Pl−1P_{l-1} in each correction computed from the same Brownian path.
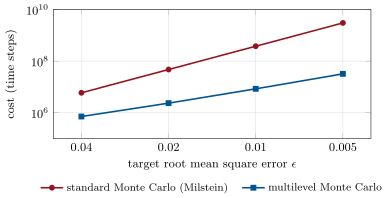
Cost of pricing a European call (S_0 = K = 100, r = 3\%, = 25\%, one year) to a target root mean square error: multilevel Monte Carlo with Milstein corrections against standard Monte Carlo at the same finest step. Data: the chapter’s tutorial, seeded.
Figure 26.5. Cost of pricing a European call (S0=K=100S_0 = K = 100, r=3%r = 3\%, σ=25%\sigma = 25\%, one year) to a target root mean square error: multilevel Monte Carlo with Milstein corrections against standard Monte Carlo at the same finest step. Data: the chapter’s tutorial, seeded.
Baca dalam konteks →
