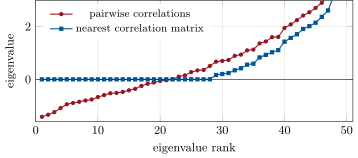
The nearest correlation matrix to a symmetric matrix is the positive semidefinite matrix with unit diagonal closest to in the Frobenius norm, a semidefinite programme that Higham (2002) solves by alternating projections with Dykstra’s correction.
 Coach
Log in
Start reading
Quantitative Finance · Glossary
The nearest correlation matrix to a symmetric matrix is the positive semidefinite matrix with unit diagonal closest to in the Frobenius norm, a semidefinite programme that Higham (2002) solves by alternating projections with Dykstra’s correction.