 المدرب
The parameter bid–offer of a position is the reserve for an unobservable input: the booked value less a prudent point of the values over the input’s plausible range.
أمثلة
Example 27.6 (Three reserves on the note)
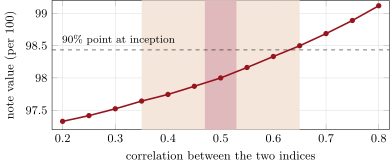
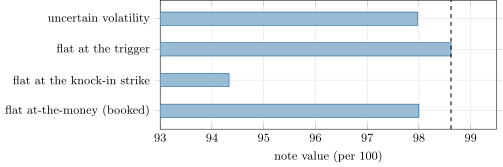
Bid–offer. Closing the vega at half a point of spread and the delta at 2 basis points costs 0.266 and 0.346 for the two vegas and less than 0.01 for the deltas: 0.621 in all per 100. Model. Four models value the note at 98.00 (flat at-the-money volatilities, booked), 94.33 (flat at the knock-in strike’s volatility, three points higher), 98.62 (flat at the trigger’s, half a point lower) and 97.98 (uncertain volatility, ). The prudent point is the highest of these for a short position, 98.62: a reserve of 0.621. Correlation. Over a plausible range of 0.35 to 0.65 the note is worth 97.64 to 98.50, and the 90% point is 98.43: a reserve of 0.433 (Figures 27.1 and 27.2).