
جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Payer and receiver swaps؟

يُعرف أيضًا باسم: payer swap · receiver swap

Definition 9.2 Markets II: Rates, FX and Credit · الفصل 9 — Interest-Rate Swaps

In a payer swap one pays the fixed rate and receives floating; in a receiver swap one receives fixed and pays floating. A payer gains when rates rise: it is short duration, like a borrower who has fixed its rate, or like a short position in a bond.
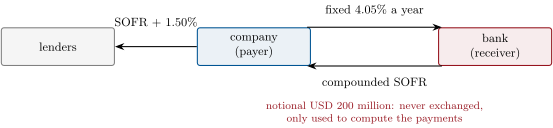
The company’s hedge. It keeps paying its lenders SOFR plus 1.50%; the swap pays it SOFR and charges 4.05%. The floating payments cancel and the company pays 5.55% fixed. Each year’s payments are netted and settled two business days after the period ends.
Figure 9.1. The company’s hedge. It keeps paying its lenders SOFR plus 1.50%; the swap pays it SOFR and charges 4.05%. The floating payments cancel and the company pays 5.55% fixed. Each year’s payments are netted and settled two business days after the period ends.

أمثلة

Example 9.3 (One year of the company’s swap)

The swap starts on 29 September 2026. On 29 September 2027 the company pays 200 000 000×4.05%×365/360=USD 8 212 500200\,000\,000 \times 4.05\% \times 365/360 = \text{USD}~8\,212\,500 and receives the overnight rate compounded over those 365 days, whatever it turns out to be; on its loan it pays the same compounded rate plus 1.5%. The floating payments cancel, and its cost is fixed.

اقرأ في الفصل →