
Todos los libros

Profesional

Apps Acerca de Coach Iniciar sesión Empezar a leer

Quantitative Finance · Glosario

¿Qué es Payer and receiver swaps?

También llamado: payer swap · receiver swap

Definition 9.2 Markets II: Rates, FX and Credit · Capítulo 9 — Interest-Rate Swaps

In a payer swap one pays the fixed rate and receives floating; in a receiver swap one receives fixed and pays floating. A payer gains when rates rise: it is short duration, like a borrower who has fixed its rate, or like a short position in a bond.
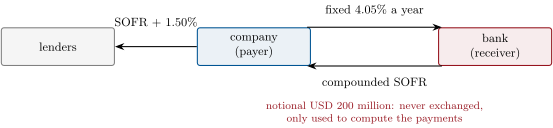
The company’s hedge. It keeps paying its lenders SOFR plus 1.50%; the swap pays it SOFR and charges 4.05%. The floating payments cancel and the company pays 5.55% fixed. Each year’s payments are netted and settled two business days after the period ends.
Figure 9.1. The company’s hedge. It keeps paying its lenders SOFR plus 1.50%; the swap pays it SOFR and charges 4.05%. The floating payments cancel and the company pays 5.55% fixed. Each year’s payments are netted and settled two business days after the period ends.

Ejemplos

Example 9.3 (One year of the company’s swap)

The swap starts on 29 September 2026. On 29 September 2027 the company pays 200 000 000×4.05%×365/360=USD 8 212 500200\,000\,000 \times 4.05\% \times 365/360 = \text{USD}~8\,212\,500 and receives the overnight rate compounded over those 365 days, whatever it turns out to be; on its loan it pays the same compounded rate plus 1.5%. The floating payments cancel, and its cost is fixed.

Leer en el capítulo →