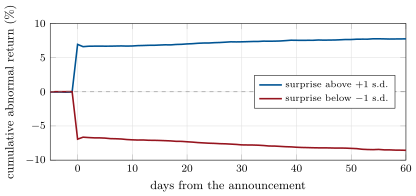
Post-earnings-announcement drift is the tendency of a stock’s abnormal returns to continue in the direction of its earnings surprise for weeks after the announcement.
s1_earnings.car. Coach
Connexion
Commencer la lecture
Quantitative Finance · Glossaire
Post-earnings-announcement drift is the tendency of a stock’s abnormal returns to continue in the direction of its earnings surprise for weeks after the announcement.
s1_earnings.car.