
جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Proxy credit spread؟

Definition 20.6 Rates, Credit, XVA and Risk · الفصل 20 — The Valuation-Adjustment Desk

A proxy credit spread is a spread assigned to a counterparty without liquid credit quotes, estimated from liquid peers that resemble it in credit quality, sector and region, or mapped to a single related name. In the European Union a proxy used for CVA capital must consider all three attributes, with at least three industry categories (public, financial, other) and four regions (Europe, North America, Asia, rest of the world).
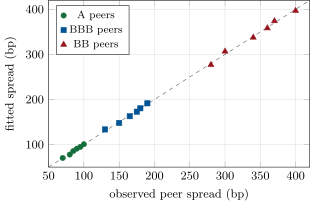
Observed against fitted ten-year spreads of the illustrative peers in the proxy regression on rating, sector and region. The points sit close to the diagonal; the client’s proxy is the model’s prediction for its cell (BB, industrials, US). Data: the chapter’s tutorial.
Figure 20.3. Observed against fitted ten-year spreads of the illustrative peers in the proxy regression on rating, sector and region. The points sit close to the diagonal; the client’s proxy is the model’s prediction for its cell (BB, industrials, US). Data: the chapter’s tutorial.

أمثلة

Example 20.7 (A proxy for the unrated client)

Regress the logarithm of eighteen illustrative ten-year peer spreads on rating (A, BBB, BB), sector (industrials, utilities, consumer) and region (US, EU) indicators. The fit’s error is 1.3% of the spread, and for the client, mapped internally to BB, industrials, US, it predicts 337.5 basis points at ten years (Figure 20.3). Applying chapter 18’s term-structure shape gives a curve from 154 basis points at one year to 338 at ten.

اقرأ في الفصل →