 Coach
A proxy credit spread is a spread assigned to a counterparty without liquid credit quotes, estimated from liquid peers that resemble it in credit quality, sector and region, or mapped to a single related name. In the European Union a proxy used for CVA capital must consider all three attributes, with at least three industry categories (public, financial, other) and four regions (Europe, North America, Asia, rest of the world).
Exemplos
Example 20.7 (A proxy for the unrated client)
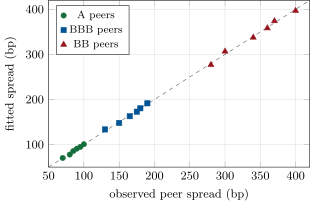
Regress the logarithm of eighteen illustrative ten-year peer spreads on rating (A, BBB, BB), sector (industrials, utilities, consumer) and region (US, EU) indicators. The fit’s error is 1.3% of the spread, and for the client, mapped internally to BB, industrials, US, it predicts 337.5 basis points at ten years (Figure 20.3). Applying chapter 18’s term-structure shape gives a curve from 154 basis points at one year to 338 at ten.