
جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Recalibration P&L؟

يُعرف أيضًا باسم: recalibration P\&L

Definition 24.8 Derivatives and Volatility · الفصل 24 — Fourier Pricing and Calibration Engineering

The recalibration P&L of a position is the change in its model value caused by refitting the model’s parameters, with the market inputs that its hedges cover held fixed; in a P&L attribution it lands in the unexplained column, and it has no hedge.
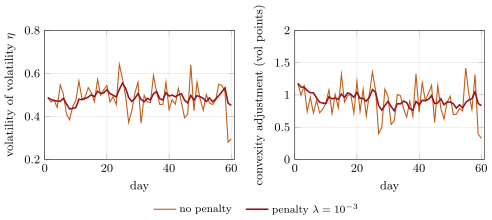
Sixty daily Heston calibrations to a noisy synthetic market. Left: the fitted volatility of volatility. Right: the convexity adjustment of a one-year volatility swap (variance-swap volatility minus volatility-swap price) implied by each day’s fit. Data: the tutorial.
Figure 24.3. Sixty daily Heston calibrations to a noisy synthetic market. Left: the fitted volatility of volatility. Right: the convexity adjustment of a one-year volatility swap (variance-swap volatility minus volatility-swap price) implied by each day’s fit. Data: the tutorial.
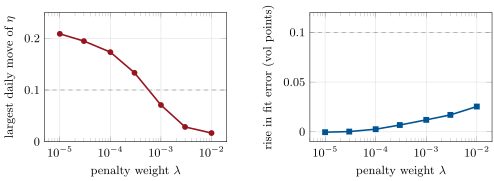
Replaying 60 days for each penalty weight. Left: the largest daily move of the volatility of volatility, against a limit of 0.1. Right: the rise in the average fit error, against a limit of 0.1 volatility point. Data: the tutorial.
Figure 24.4. Replaying 60 days for each penalty weight. Left: the largest daily move of the volatility of volatility, against a limit of 0.1. Right: the rise in the average fit error, against a limit of 0.1 volatility point. Data: the tutorial.

أمثلة

Example 24.9 (Sixty days with and without a penalty)

Unpenalised, the daily fits move η\eta by as much as 0.235 in a day, and the convexity adjustment of a one-year volatility swap (chapter 14) changes by 0.36 volatility point a day (standard deviation). With λ=10−3\lambda=10^{-3} the largest daily move of η\eta is 0.071, the adjustment’s daily changes fall to 0.07 volatility point, and the average fit error rises from 0.291 to 0.303 volatility point (Figure 24.3). On day 59, where the free fit took η\eta from 0.51 to 0.28, the penalised adjustment moves by 0.18 volatility point instead of 0.93.

اقرأ في الفصل →