
सभी किताबें

पेशेवर

ऐप्स परिचय Coach लॉग इन पढ़ना शुरू करें

Quantitative Finance · शब्दावली

Recalibration P&L क्या है?

अन्य नाम: recalibration P\&L

Definition 24.8 Derivatives and Volatility · अध्याय 24 — Fourier Pricing and Calibration Engineering

The recalibration P&L of a position is the change in its model value caused by refitting the model’s parameters, with the market inputs that its hedges cover held fixed; in a P&L attribution it lands in the unexplained column, and it has no hedge.
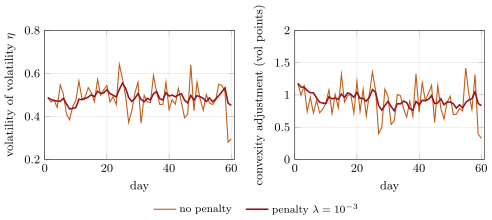
Sixty daily Heston calibrations to a noisy synthetic market. Left: the fitted volatility of volatility. Right: the convexity adjustment of a one-year volatility swap (variance-swap volatility minus volatility-swap price) implied by each day’s fit. Data: the tutorial.
Figure 24.3. Sixty daily Heston calibrations to a noisy synthetic market. Left: the fitted volatility of volatility. Right: the convexity adjustment of a one-year volatility swap (variance-swap volatility minus volatility-swap price) implied by each day’s fit. Data: the tutorial.
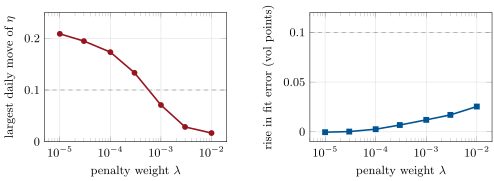
Replaying 60 days for each penalty weight. Left: the largest daily move of the volatility of volatility, against a limit of 0.1. Right: the rise in the average fit error, against a limit of 0.1 volatility point. Data: the tutorial.
Figure 24.4. Replaying 60 days for each penalty weight. Left: the largest daily move of the volatility of volatility, against a limit of 0.1. Right: the rise in the average fit error, against a limit of 0.1 volatility point. Data: the tutorial.

उदाहरण

Example 24.9 (Sixty days with and without a penalty)

Unpenalised, the daily fits move η\eta by as much as 0.235 in a day, and the convexity adjustment of a one-year volatility swap (chapter 14) changes by 0.36 volatility point a day (standard deviation). With λ=10−3\lambda=10^{-3} the largest daily move of η\eta is 0.071, the adjustment’s daily changes fall to 0.07 volatility point, and the average fit error rises from 0.291 to 0.303 volatility point (Figure 24.3). On day 59, where the free fit took η\eta from 0.51 to 0.28, the penalised adjustment moves by 0.18 volatility point instead of 0.93.

अध्याय में पढ़ें →