Tous les livres

Professionnel

Applis À propos Coach Connexion Commencer la lecture

Quantitative Finance · Glossaire

Qu'est-ce que « Regularisation path » ?

Definition 4.2 Machine Learning for Markets · Chapitre 4 — Linear and Regularised Baselines

The regularisation path of a penalised estimator is its solution, or its validation score, as a function of the penalty λ\lambda; the penalty is chosen at the path’s best purged cross-validated score.
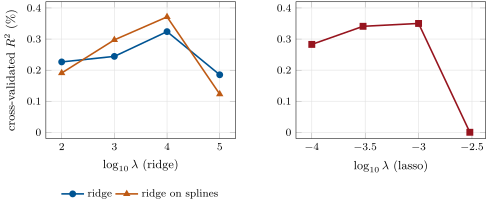
Regularisation paths: pooled out-of-fold R-squared of three purged folds of the twenty training years, as a function of the penalty. Ridge peaks at = 104 (training folds of about 80 000 rows), the lasso at 10-3; one step further the lasso sets every coefficient to zero and scores zero. Data: ml_baselines.paths.
Figure 4.1. Regularisation paths: pooled out-of-fold R-squared of three purged folds of the twenty training years, as a function of the penalty. Ridge peaks at λ=104\lambda = 10^4 (training folds of about 80 000 rows), the lasso at 10−310^{-3}; one step further the lasso sets every coefficient to zero and scores zero. Data: ml_baselines.paths.
Lire dans le chapitre →
