
Todos los libros

Profesional

Apps Acerca de Coach Iniciar sesión Empezar a leer

Quantitative Finance · Glosario

¿Qué es Simulator calibration, implementation shortfall, arrival price?

También llamado: simulator calibration · implementation shortfall · arrival price

Definition 19.4 Research Craft: Predictors, Backtests, Measurement, Portfolios · Capítulo 19 — Simulation Versus Live

Simulator calibration adjusts a simulator’s parameters (latency, queue model, fill probabilities) so that its output matches live outcomes. The implementation shortfall of an order (Perold, 1988) is the difference between the P&L of a paper portfolio traded in full at the decision time’s price and the P&L actually realised; the price at the decision time, or at the order’s arrival in the market, is its arrival price.
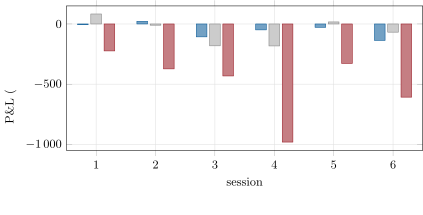
The quoter’s P&L in each of six simulated sessions: the research replay, the replay of a second realisation of the same hour (with the live latencies), and live. The live loss exceeds both in every session. Data: rs_simlive.decomposition.
Figure 19.2. The quoter’s P&L in each of six simulated sessions: the research replay, the replay of a second realisation of the same hour (with the live latencies), and live. The live loss exceeds both in every session. Data: rs_simlive.decomposition.
Leer en el capítulo →