Coach
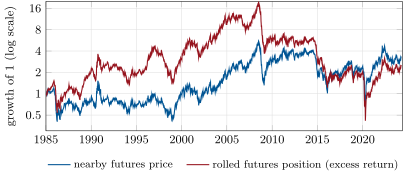
For a fully collateralised, rolled long futures position, the spot return is the change in the nearby futures price; the roll yield is the rest of the futures’ return, earned as each held contract converges to the nearby price (positive in backwardation, negative in contango); the collateral return is the interest earned on the cash that backs the position. Their sum is the total return.