
Semua buku

Profesional

Aplikasi Tentang Pelatih Masuk Mulai membaca

Quantitative Finance · Glosarium

Apa itu Stress capital buffer, G-SIB surcharge?

Dikenal juga sebagai: stress capital buffer · G-SIB surcharge

Definition 5.3 The Desk and the Firm · Bab 5 — The Bank Markets Division

A stress capital buffer is a capital buffer set from the capital a bank would lose in the supervisor’s severe stress scenario, added to its minimum ratio. A G-SIB surcharge is an additional capital buffer required of a global systemically important bank, set by a score of its size, interconnectedness, complexity, cross-jurisdictional activity and substitutability.
One bank’s two requirements at the end of 2025: CET1 over risk-weighted assets (a 4.5% minimum, a 2.5% stress capital buffer and a 4.5% GSIB surcharge, 11.5%, against 14.6% held) and Tier 1 over leverage exposure (3.0% plus a 2.0% buffer, against 5.8%). Data: JPMorgan Chase & Co., Form 10-K for 2025.
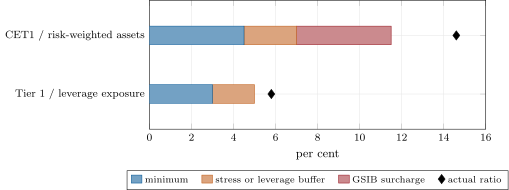
Figure 5.2. One bank’s two requirements at the end of 2025: CET1 over risk-weighted assets (a 4.5% minimum, a 2.5% stress capital buffer and a 4.5% GSIB surcharge, 11.5%, against 14.6% held) and Tier 1 over leverage exposure (3.0% plus a 2.0% buffer, against 5.8%). Data: JPMorgan Chase & Co., Form 10-K for 2025.
Baca dalam konteks →