Tous les livres

Professionnel

Applis À propos Coach Connexion Commencer la lecture

Quantitative Finance · Glossaire

Qu'est-ce que « Structural break, CUSUM test » ?

Aussi appelé : structural break · CUSUM test

Definition 13.3 Research Craft: Predictors, Backtests, Measurement, Portfolios · Chapitre 13 — Half-Life, Decay and Stability

A structural break is a change, at some date, in the parameters of the process generating a series (here, the mean of a predictor’s IC). The CUSUM test of Brown, Durbin and Evans (1975) cumulates the standardised recursive residuals (each observation minus the mean of those before it, rescaled) and rejects constancy when the path leaves a pair of lines that widen linearly with time, ±a(K+2k/K)\pm a(\sqrt K + 2k/\sqrt K) with a=0.948a = 0.948 at 5% for KK residuals.

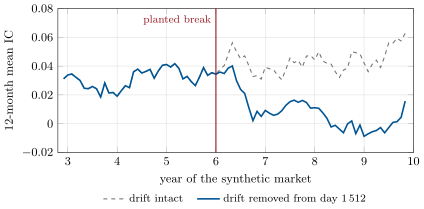
Twelve-month rolling mean of the earnings surprise’s monthly IC on firm.synthmkt, with the post-earnings drift intact and with it removed from the start of year 7 (day 1 512). The sup-F test finds the break (p-value 0.013); the CUSUM does not; in this market a 70% cut is found by neither.
Figure 13.2. Twelve-month rolling mean of the earnings surprise’s monthly IC on firm.synthmkt, with the post-earnings drift intact and with it removed from the start of year 7 (day 1 512). The sup-F test finds the break (p-value 0.013); the CUSUM does not; in this market a 70% cut is found by neither.
Lire dans le chapitre →