Tous les livres

Professionnel

Applis À propos Coach Connexion Commencer la lecture

Quantitative Finance · Glossaire

Qu'est-ce que « Subordinator » ?

Definition 6.8 Quantitative Methods · Chapitre 6 — Jump Processes

A subordinator is a Lévy process with nondecreasing paths; running a Brownian motion on it as a clock, Xt=θGt+σWGtX_t = \theta G_t + \sigma W_{G_t}, gives a Lévy process whose exponent is the subordinator’s Laplace exponent evaluated at iuθ−σ2u2/2\iu u\theta - \sigma^2u^2/2.

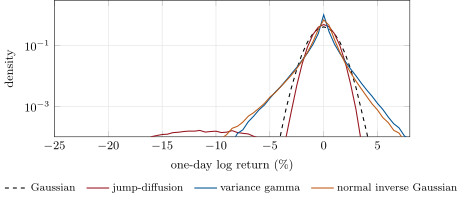
Densities of one day’s log return, on a log scale, for four Lévy models with the same variance (a daily standard deviation of 0.98%): the Gaussian, the chapter’s calibrated jump-diffusion, variance gamma (= -0.1, = 0.013) and normal inverse Gaussian (= 58, = -11.6), the last two with one-day excess kurtoses of 8.5 and 12.5. Histograms of 2 million simulated days each, with bins of 0.5 point. Data: the chapter’s tutorial, seeded.
Figure 6.2. Densities of one day’s log return, on a log scale, for four Lévy models with the same variance (a daily standard deviation of 0.98%): the Gaussian, the chapter’s calibrated jump-diffusion, variance gamma (θ=−0.1\theta = -0.1, ν=0.013\nu = 0.013) and normal inverse Gaussian (α=58\alpha = 58, β=−11.6\beta = -11.6), the last two with one-day excess kurtoses of 8.5 and 12.5. Histograms of 2 million simulated days each, with bins of 0.5 point. Data: the chapter’s tutorial, seeded.
Lire dans le chapitre →