Semua buku

Profesional

Aplikasi Tentang Pelatih Masuk Mulai membaca

Quantitative Finance · Glosarium

Apa itu Super-replication price?

Definition 1.15 Derivatives and Volatility · Bab 1 — No Arbitrage and the Fundamental Theorems

The super-replication price of a claim gg is the lowest cost of a portfolio of traded assets that pays at least gg in every state: inf⁡{p⋅θ:Dθ≥g}\inf\{p\cdot\theta: D\theta\ge g\}. The sub-replication price is the highest cost of one that pays at most gg.

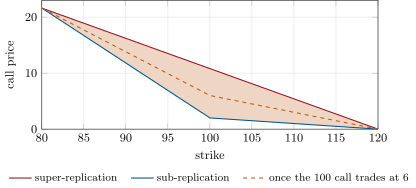
The no-arbitrage interval of a call in the trinomial market, by strike. Once one option trades (the 100 call at 6.00) the market is complete and every other strike has a single price, the dashed line, inside the band. Data: the tutorial.
Figure 1.3. The no-arbitrage interval of a call in the trinomial market, by strike. Once one option trades (the 100 call at 6.00) the market is complete and every other strike has a single price, the dashed line, inside the band. Data: the tutorial.
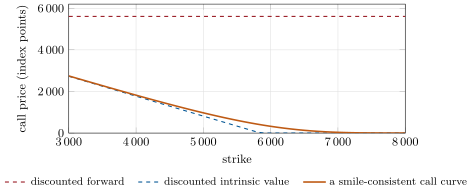
Where a call price can lie: between the discounted intrinsic value P (F-K,0) and the discounted forward PF, decreasing and convex in the strike. The solid curve is the chain of the weekend problem (forward 5 850, one year, a skewed smile). Illustrative parameters.
Figure 1.4. Where a call price can lie: between the discounted intrinsic value Pmax⁡(F−K,0)P\max(F-K,0) and the discounted forward PFPF, decreasing and convex in the strike. The solid curve is the chain of the weekend problem (forward 5 850, one year, a skewed smile). Illustrative parameters.
Baca dalam konteks →