
جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Theory of storage, convenience yield؟

يُعرف أيضًا باسم: theory of storage · convenience yield

Definition 10.3 Markets III: Commodities, Energy and Crypto · الفصل 10 — Forward Curves, Storage and Convenience Yield

The theory of storage (Kaldor, Working, Brennan) explains the futures–spot spread by the cost of storage and a benefit of holding inventory. That benefit, per unit of value and time, is the convenience yield ycy_c: the value of being able to use the commodity now, avoiding a stock-out, keeping a plant running. With it,
Ft,T=St e(r+u−yc) τ.F_{t,T} = S_t\,e^{(r + u - y_c)\,\tau}.
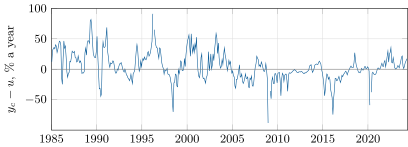
Net convenience yield of WTI implied by contracts 1 and 2 and the 3-month Treasury bill, monthly means of daily values, January 1985 to March 2024 (months below -100\%, such as April 2020, are off the chart). The median month is close to zero; the curve was in backwardation on 45% of days. Data: EIA; FRED DTB3.
Figure 10.2. Net convenience yield of WTI implied by contracts 1 and 2 and the 3-month Treasury bill, monthly means of daily values, January 1985 to March 2024 (months below −100%-100\%, such as April 2020, are off the chart). The median month is close to zero; the curve was in backwardation on 45% of days. Data: EIA; FRED DTB3.

أمثلة

Example 10.5 (Reading a spread)

The front WTI contract is at $80.00 and the second at $79.40, a month apart, with the rate at 4%. The net convenience yield is 0.04−12ln⁡(79.40/80.00)=13.0%0.04 - 12\ln(79.40/80.00) = 13.0\% a year: the market pays about 13% a year above financing to hold oil now. With the second at $80.60, it is −5.0%-5.0\%: storage is being paid for.

اقرأ في الفصل →