 Coach
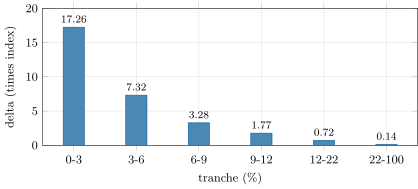
The tranche delta is the notional of index protection whose value changes as much as the tranche’s, per unit of tranche notional, when every name’s spread moves together by a small amount, with the base correlations held.
उदाहरण
Example 15.7 (Deltas across the structure)
The deltas of the six tranches of Example 15.4 are 17.3, 7.32, 3.28, 1.77, 0.72 and 0.14 (Figure 15.3): EUR 10 million of equity tranche moves like EUR 173 million of index. Hedging the equity with the mezzanine takes times the notional.