Coach
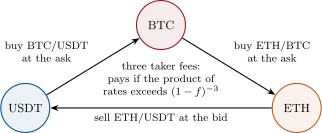
Triangular arbitrage is a cycle of three trades on one venue that starts and ends in the same asset through two others, for example USDT into bitcoin, bitcoin into ether and ether back into USDT, executed when the product of the three exchange rates, after fees, exceeds one.