Todos os livros

Profissional

Apps Sobre Coach Entrar Começar a ler

Quantitative Finance · Glossário

O que é Vasicek model?

Definition 7.3 Rates, Credit, XVA and Risk · Capítulo 7 — Short-Rate Models

The Vasicek model (1977) makes the short rate an Ornstein–Uhlenbeck process, drt=κ(xˉ−rt) dt+σ dWtdr_t = \kappa(\bar x-r_t)\,dt+\sigma\,dW_t: mean reversion at speed κ\kappa to a level xˉ\bar x, normal increments, negative rates possible.
Normal volatility of zero rates, B( )/, in a one-factor Gaussian model with = 80 basis points: mean reversion damps the volatility of long rates (69.1 basis points at ten years with =3\%, 50.6 with =10\%). Data: the chapter’s tutorial.
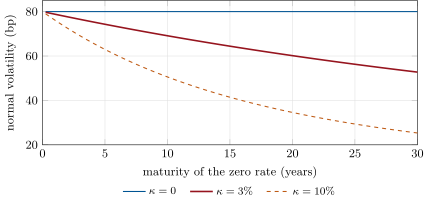
Figure 7.1. Normal volatility of zero rates, σB(τ)/τ\sigma B(\tau)/\tau, in a one-factor Gaussian model with σ=80\sigma = 80 basis points: mean reversion damps the volatility of long rates (69.1 basis points at ten years with κ=3%\kappa=3\%, 50.6 with κ=10%\kappa=10\%). Data: the chapter’s tutorial.
Ler no capítulo →
